Moving From a Rental to a New Home: A Planning Calendar
Homebuyer Tips Nov 12, 2026 · 5 min read
Alta Homes Team
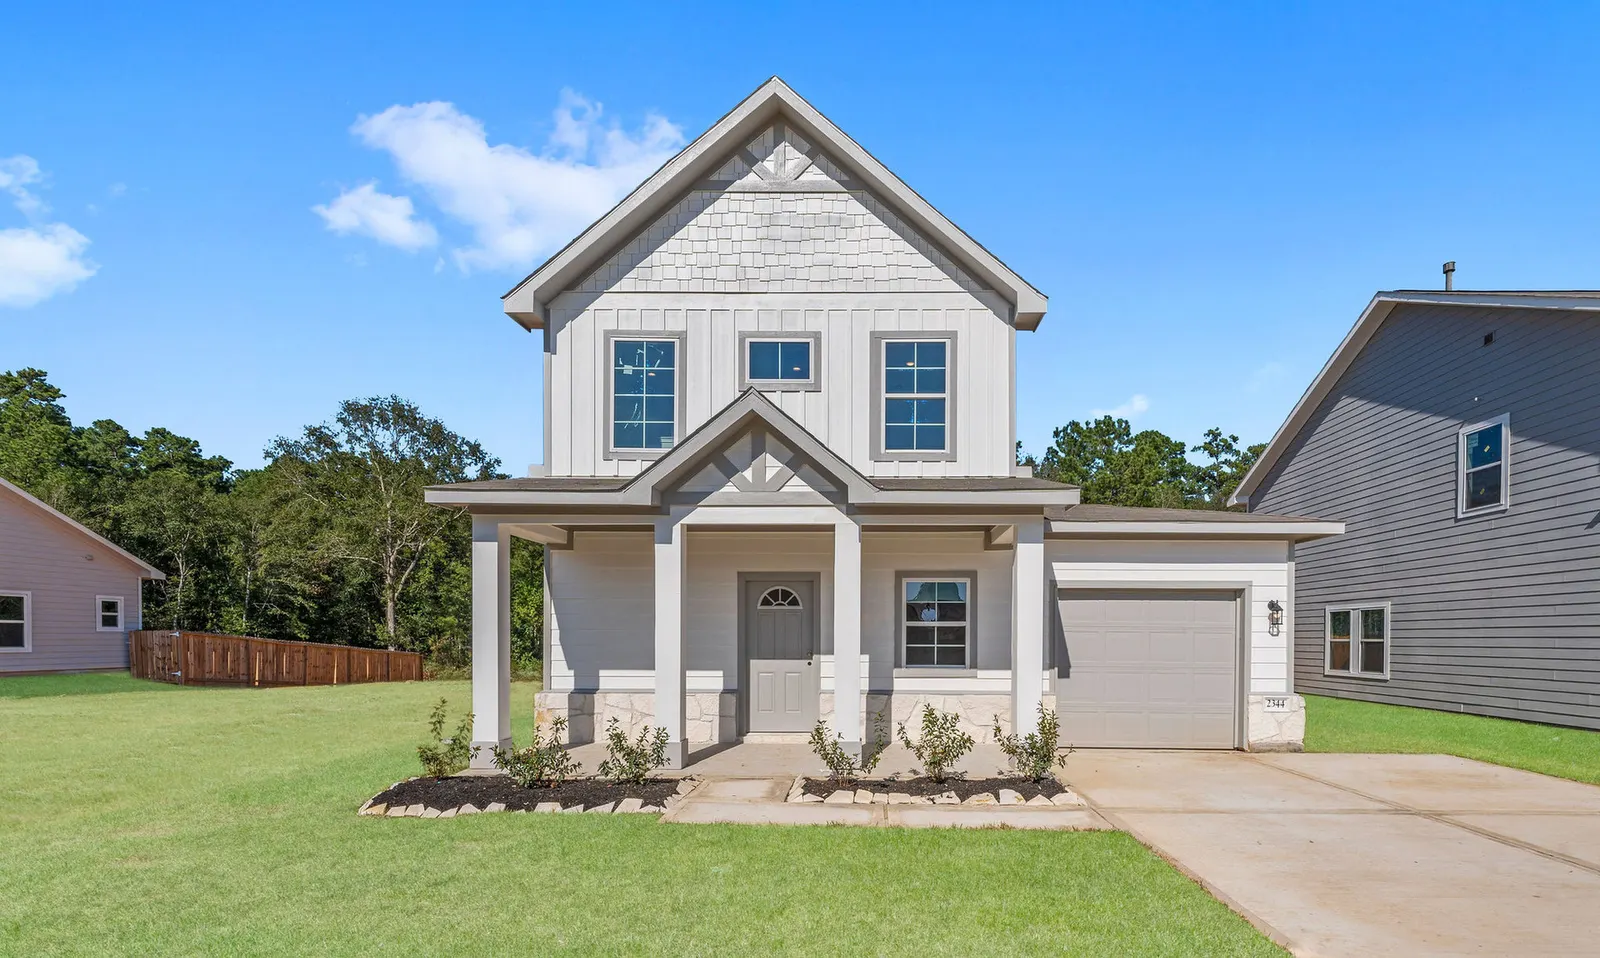
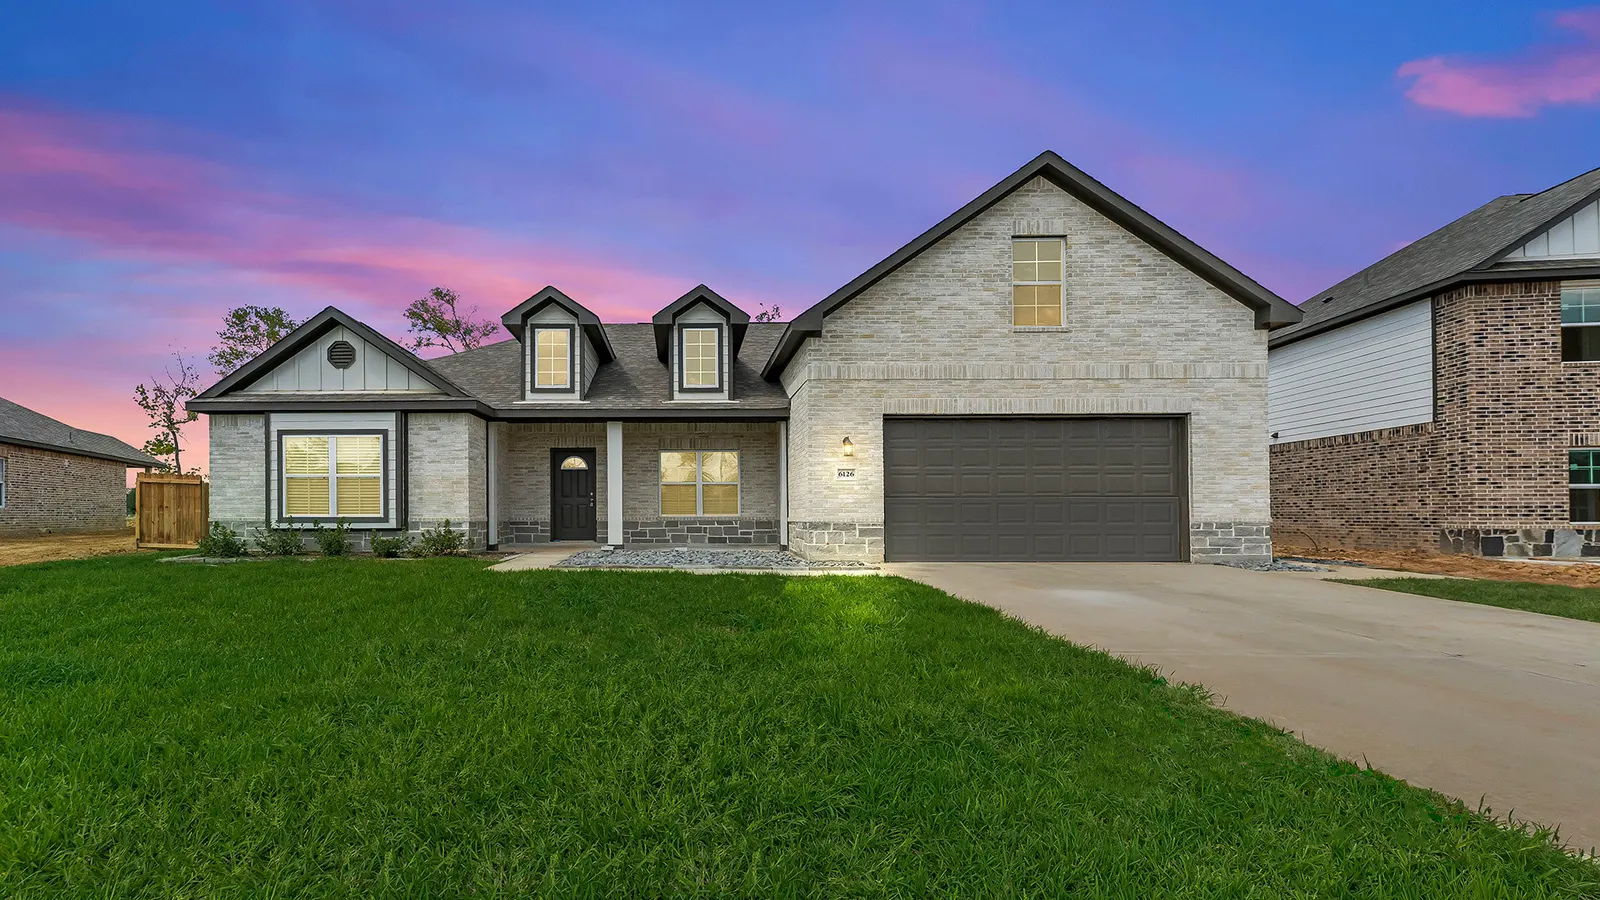
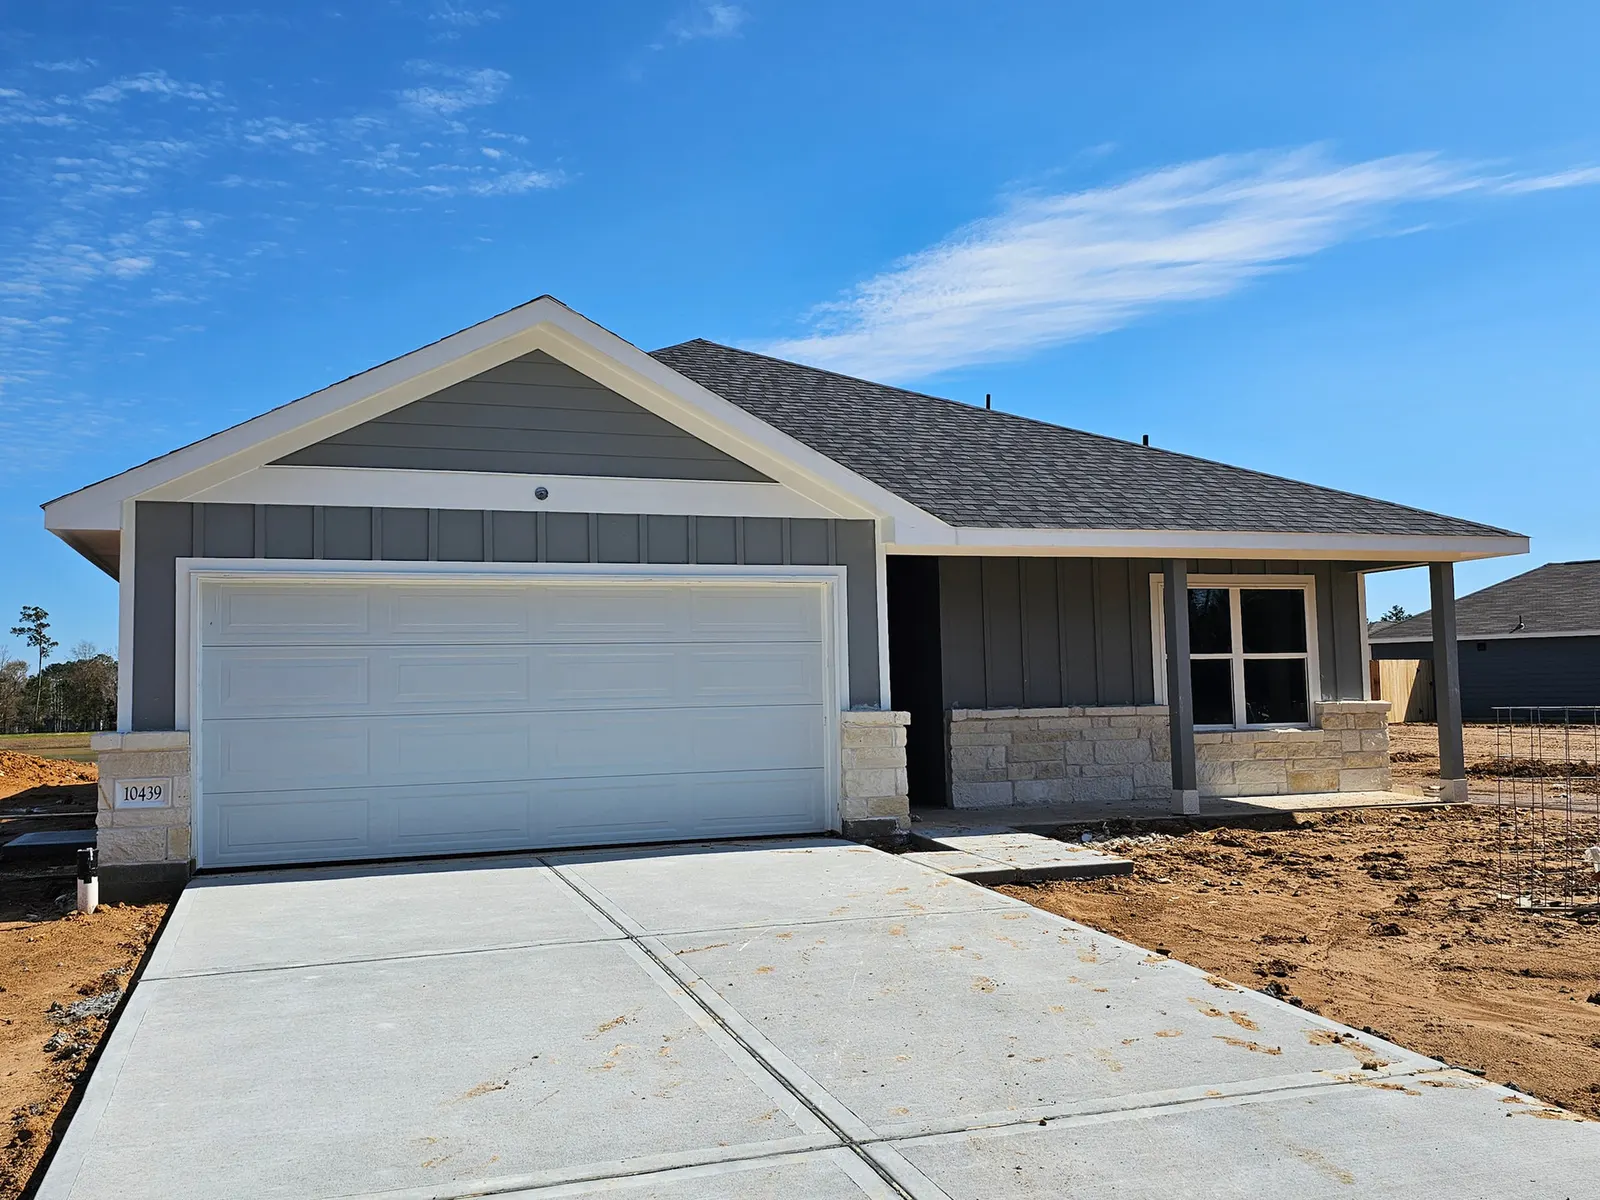
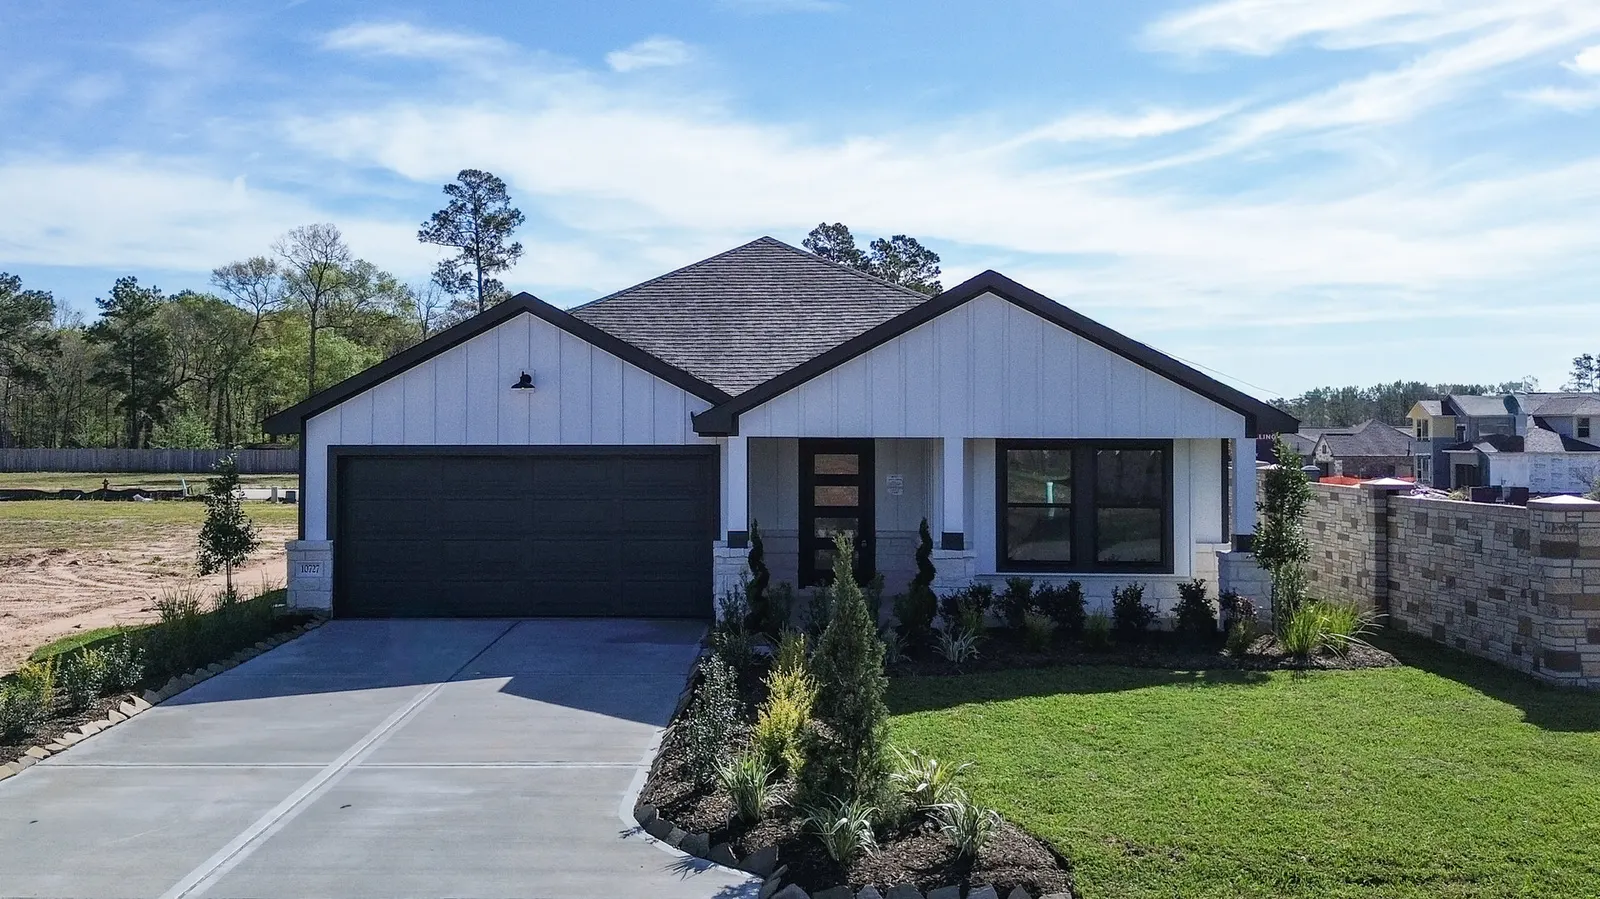
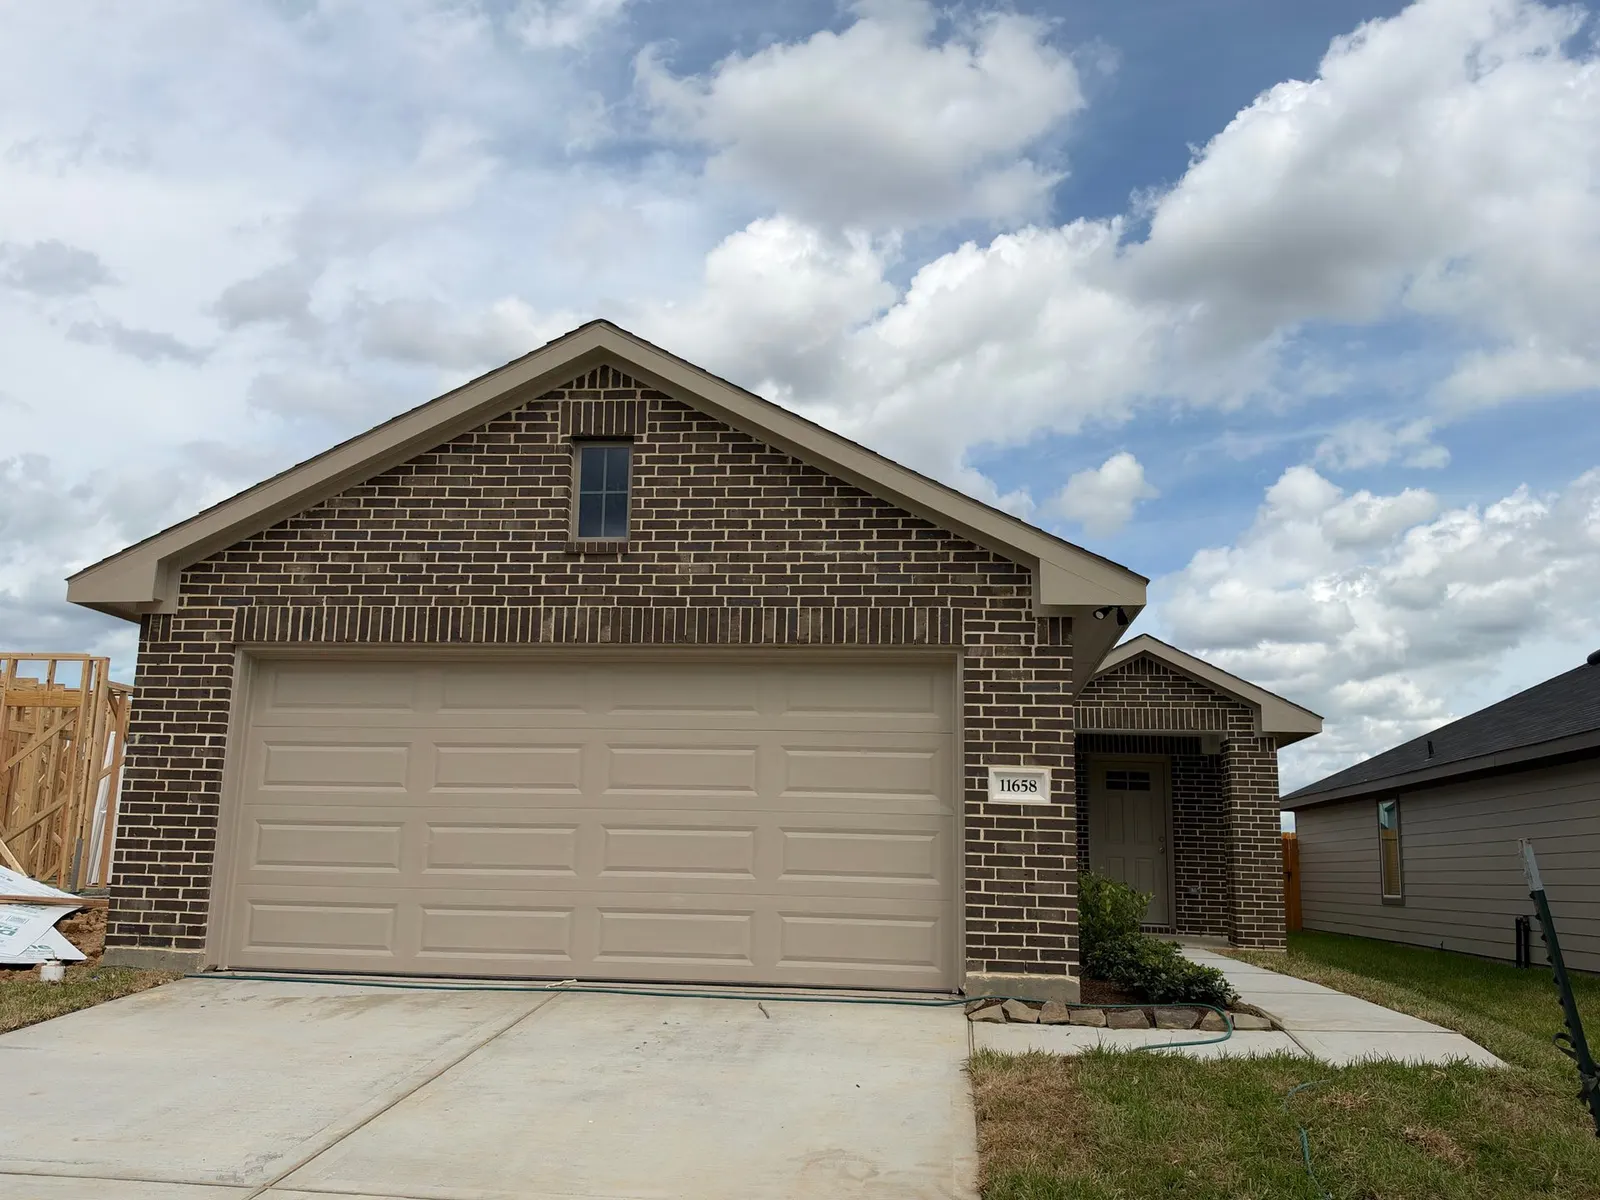
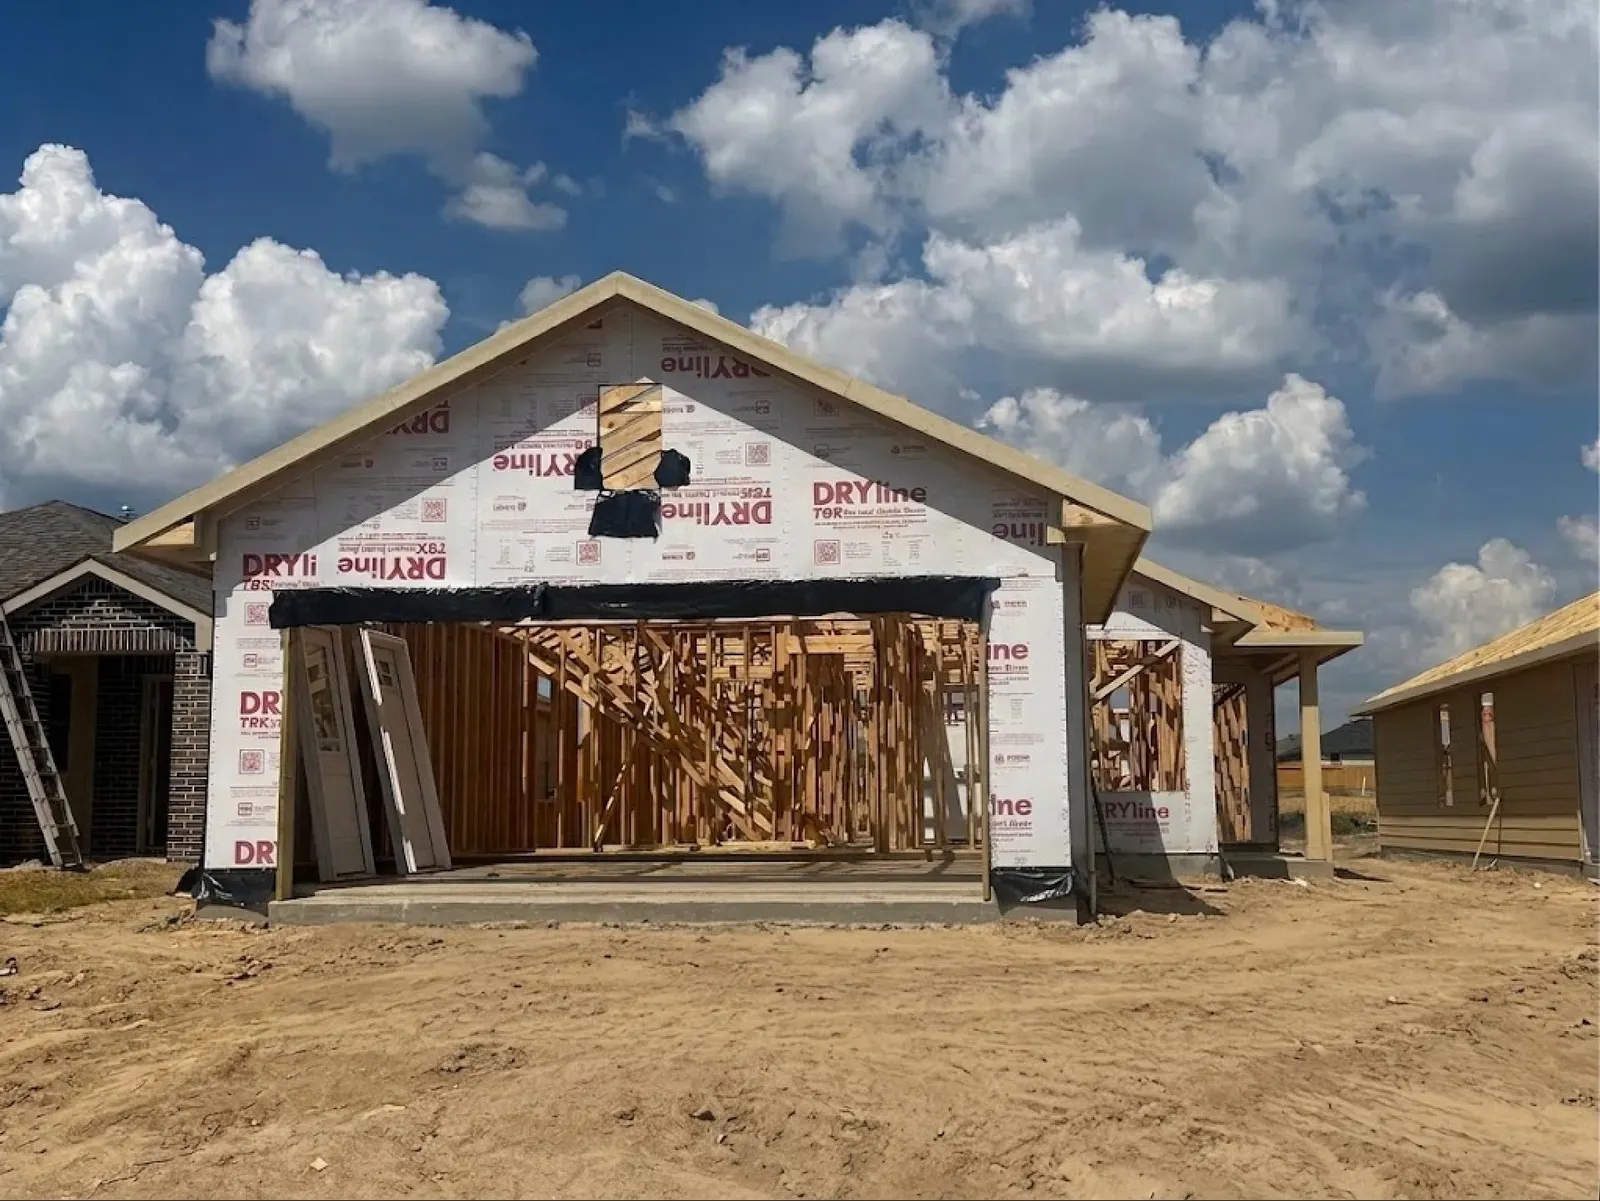
An Alta home from our gallery. Check the current listing and purchase schedule for the specific home you want to buy.
If your lease is ending, the right home needs to fit your calendar as well as your budget. Whether you are looking in Conroe, Willis, or elsewhere in Montgomery County, keep three dates separate: your lease-end date, the home’s expected completion, and when you can take possession.
Do not give your landlord notice based only on an estimated completion month. Our quick move-in guide explains that a home can be complete or still under construction. Closing also depends on financing and other requirements. Before giving notice, ask your Home Advisor and lender whether closing is scheduled and what could still change it.
First: read the lease before picking moving day
Record the notice deadline, required delivery method, lease-end date, and cleaning and key-return steps. Keep the notice and proof of delivery. If your lease runs beyond closing, review early-termination, reletting, and sublease terms, then ask the property manager in writing what ending it early would cost.
If you must give notice before closing is firm, price a short extension or month-to-month stay in writing. Compare it with overlapping rent and other temporary housing. Do not count on an extension until the landlord agrees to the dates and cost.
Bring the lease-end date and notice deadline to your home search. We include the lease-end date in the first-visit checklist at the end of our guide to buying an Alta home.
Build one calendar for the purchase
List each milestone, what to record, and who supplies the update. Label dates estimated or confirmed, and replace an old date when a new one is agreed.
Swipe or scroll to see all columns.
| Milestone | What to record | Update from |
|---|---|---|
| Home completion | Current estimate and remaining work. | Home Advisor. |
| Financing | Requested documents, lender deadlines, and rate-lock expiration. | Lender. |
| Walkthrough | Appointment, observations, and follow-up. | Home Advisor. |
| Closing | Appointment and remaining requirements. | Lender and closing team. |
| Possession and keys | When the purchase agreement allows access. | Purchase documents and closing team. |
| Rental return | Notice, cleaning, key return, and service obligations. | Lease and property manager. |
Buying while construction continues? Our construction timeline guide helps you ask about the milestones behind the estimate.
Before you book: compare the change fees
Request mover quotes showing the deposit, cancellation deadline, rescheduling charge, and storage terms. A low price can become expensive if it cannot move with your closing date. Movers, deliveries, and installers need possession and access to the home.
Keep moving expenses separate from the cash needed to buy: budget for the move, deposits, utility setup, storage, and any housing overlap. Ask the lender what available funds must remain for closing before spending them on the move.
If the closing date moves
Keep a short fallback plan with real prices:
- The mover’s rescheduling deadline and charge.
- A storage option and its minimum rental period.
- A place you could stay for a week, including pets if needed.
- The cost of the rental extension or overlapping housing you already checked.
- The rental services that must stay active under your lease and return arrangements.
Keep essential documents, medications, work items, and a few days of clothing with you rather than on the truck.
Arrange services for the exact address
Ask your Home Advisor which electric, water, trash, and internet providers serve the home and whether any accounts remain in the builder’s name until closing. Confirm availability directly with each provider, then record its start date, deposit, installation appointment, and any required access. Neighborhood internet advertising does not confirm service at an individual address.
Use the official USPS change-of-address service and notify banks, your employer, insurers, and regular senders of the new address. Set the forwarding date to match your move. Once you arrive, our first-month checklist covers Texas license updates and homestead paperwork.
Reserve time for the closing documents
For most mortgages, you must receive the Closing Disclosure at least three business days before closing. The CFPB recommends checking delivery arrangements at least a week ahead. Compare it with your most recent Loan Estimate, including the terms, payment, and cash to close.
For this waiting period, Saturdays count; Sundays and federal legal holidays do not. Ask your lender to confirm the timeline during a holiday week. Three types of late change can restart the waiting period: an APR that becomes inaccurate under the rule, a change to the loan product, or an added prepayment penalty. Most other corrections do not require a new three-day wait.
Line up homeowners insurance early and confirm the lender’s proof-of-coverage requirements. Ask the closing team what identification and payment method to bring. Verify wire instructions by calling a previously established, trusted title-company number. Do not act on emailed changes until independently verified; the CFPB warns that scammers target closing funds.
Finish the rental return with a paper trail
Photograph the rental’s condition, complete the agreed return steps, and save key-return and service-account records. Give your landlord a forwarding address in writing.
Under Texas Property Code Chapter 92, the deposit is generally due within 30 days after you surrender the rental, subject to lawful deductions. The landlord need not return it until you provide a written forwarding address. Follow any valid advance-notice requirement in your lease, and do not withhold last month’s rent expecting the deposit to cover it. Read your lease and the statute for the requirements that apply to you.
Browse available Alta homes, then tell us your lease-end date and notice deadline. Those two details help us discuss homes against the calendar you actually have.
This is general planning information, not legal or lending advice. Your agreements and applicable law determine your obligations; your lender and closing team confirm the transaction’s requirements.