Downsizing in Willis or Conroe: Costs and Considerations
Maintenance Jun 24, 2026 · 5 min read Updated: Sep 8, 2026
A smaller home can mean less space to maintain and a layout that better fits how you live now. Whether it also lowers your costs depends on your current home, the next home, and the expenses involved in moving.
If you’re considering Willis, Conroe, or Montgomery, compare the financial picture alongside the daily routines you want to keep. Downsizing should make sense on both counts.
Estimate what your current home can contribute
Start with a realistic sale-price range based on comparable homes, then request a current mortgage payoff and an estimate of selling expenses. Repairs, transaction costs, moving, and temporary housing can reduce the amount available for your next purchase.
Keep these numbers separate:
- Estimated sale price.
- Outstanding mortgage and other liens.
- Selling and preparation costs.
- Expected net proceeds.
- Savings you want to retain after buying.
Equity is not the same as cash available at closing. An online valuation or a national homeowner average cannot tell you what your own sale will produce. If you are deciding between a cash purchase and financing, review the effect on your remaining savings and retirement plans with the relevant adviser.
Compare the full cost of staying and moving
A smaller purchase price does not automatically create a smaller monthly budget. Obtain estimates for the new home’s property taxes, insurance, utilities, association dues, maintenance, and any mortgage payment. Compare these with what you actually spend now.
For the existing home, include work you expect to undertake if you stay. For the new home, include moving, storage, furnishings, and any items outside the standard package. Consider how much yard work, cleaning, and maintenance you want to handle yourself or pay someone else to do.
If you plan to buy before selling, ask your lender about qualifying while both homes are owned. Discuss the cost of overlapping payments and what would happen if the sale takes longer than expected. Do not rely on a particular sale price or closing date until the necessary agreements are in place.
Check tax questions before deciding
A qualifying home sale may be eligible for a federal exclusion of some gain, but ownership, use, timing, and other rules apply. The IRS guide to the sale of a home explains the framework. A tax professional can assess your own sale.
Texas residence-homestead exemptions and age-related benefits have separate requirements. Review the Texas Comptroller’s exemption guidance and contact the appraisal district about the new property. Do not assume your current tax bill or tax ceiling transfers unchanged to a different home.
Get these answers before treating a projected tax reduction as money available to spend elsewhere.
Choose a layout, not just a smaller square-foot total
Bring measurements for the furniture you intend to keep. Check doorways, circulation around the bed, bathroom access, kitchen storage, and the relationship between the garage and living areas. Consider where guests will stay and where hobbies or work will happen.
If long-term mobility is part of the decision, inspect the actual entry, thresholds, shower configuration, and interior clearances. A single-story floor plan is not automatically designed for every accessibility need. Ask about the specific features that matter to you and whether changes are available.
A home can be smaller yet function better if the rooms you use most are proportioned well. It can also feel too small if necessary storage moves to a paid unit or guests require another arrangement. Include those tradeoffs in the comparison.
Test the location against your routine
Visit at different times. Drive to your grocery store, pharmacy, medical providers, and the people you see regularly. Check appointment availability with healthcare providers rather than relying only on proximity to a medical building.
If time outdoors is a priority, visit the walking areas, parks, or lake destinations you expect to use. Confirm access, parking, and any fees with the operator. A nearby attraction may still require driving; a community’s address does not establish walkability.
Look at the homesite as well as the neighborhood. The yard, slope, orientation, neighboring lots, and ongoing construction may matter as much as the floor plan.
Alta communities to compare
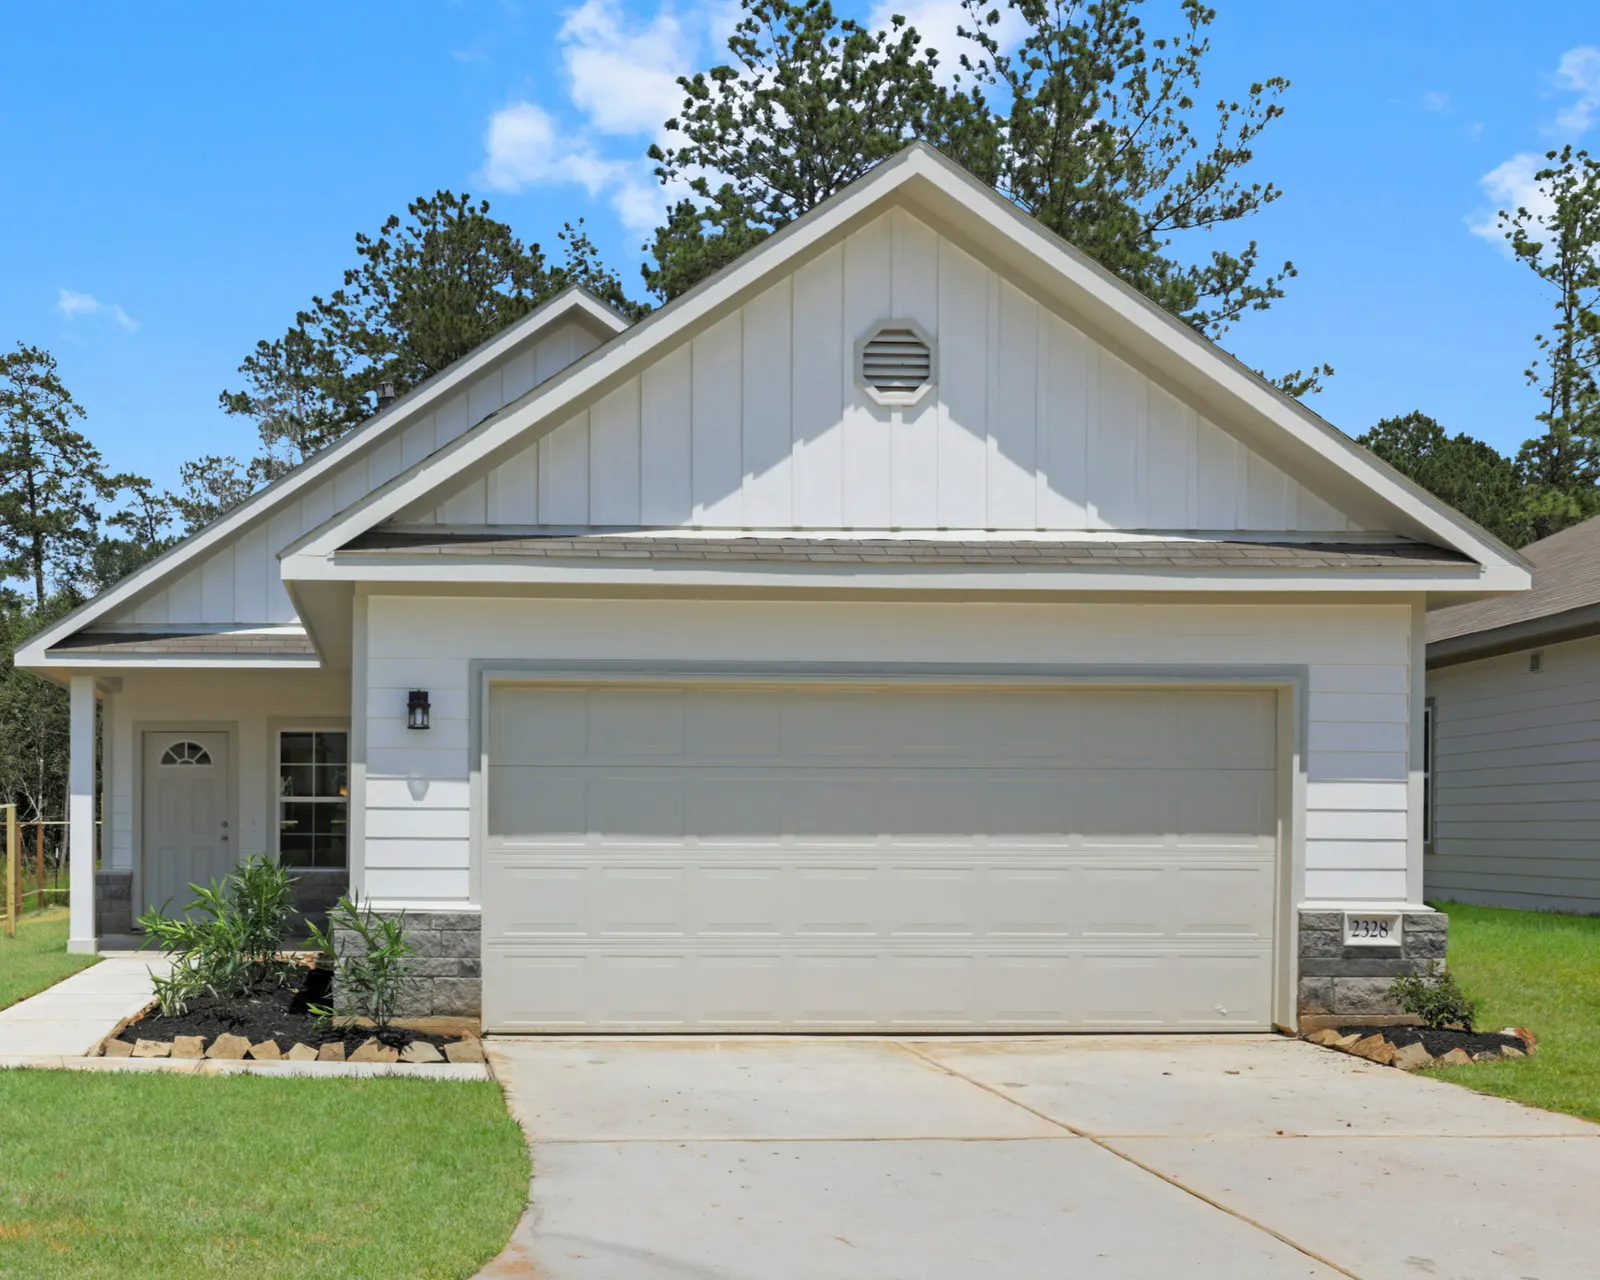
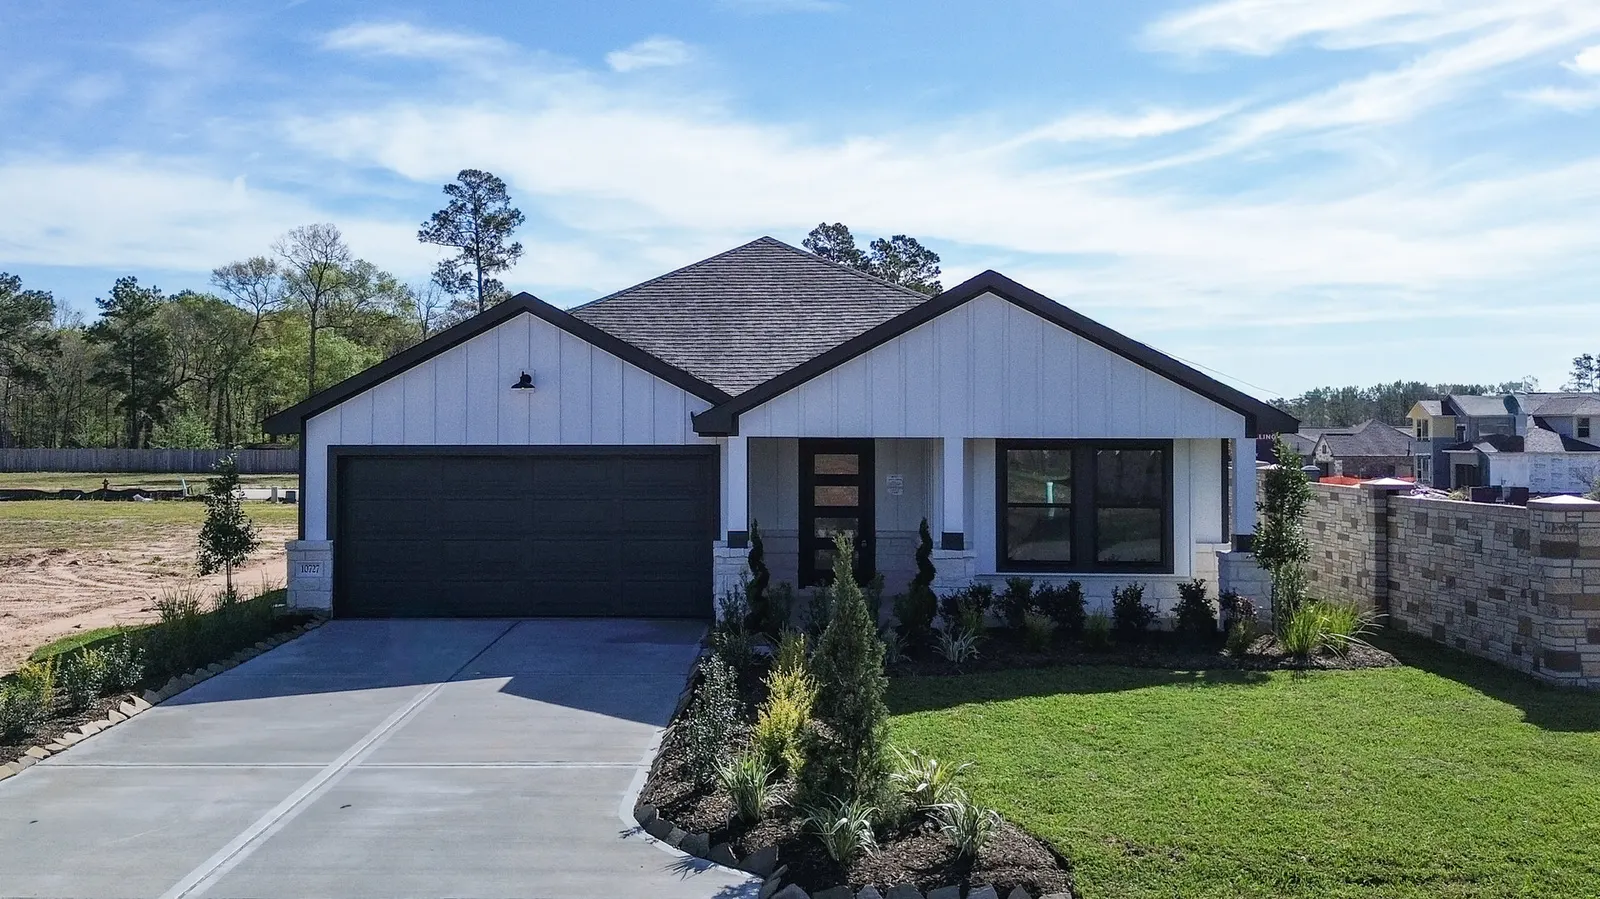
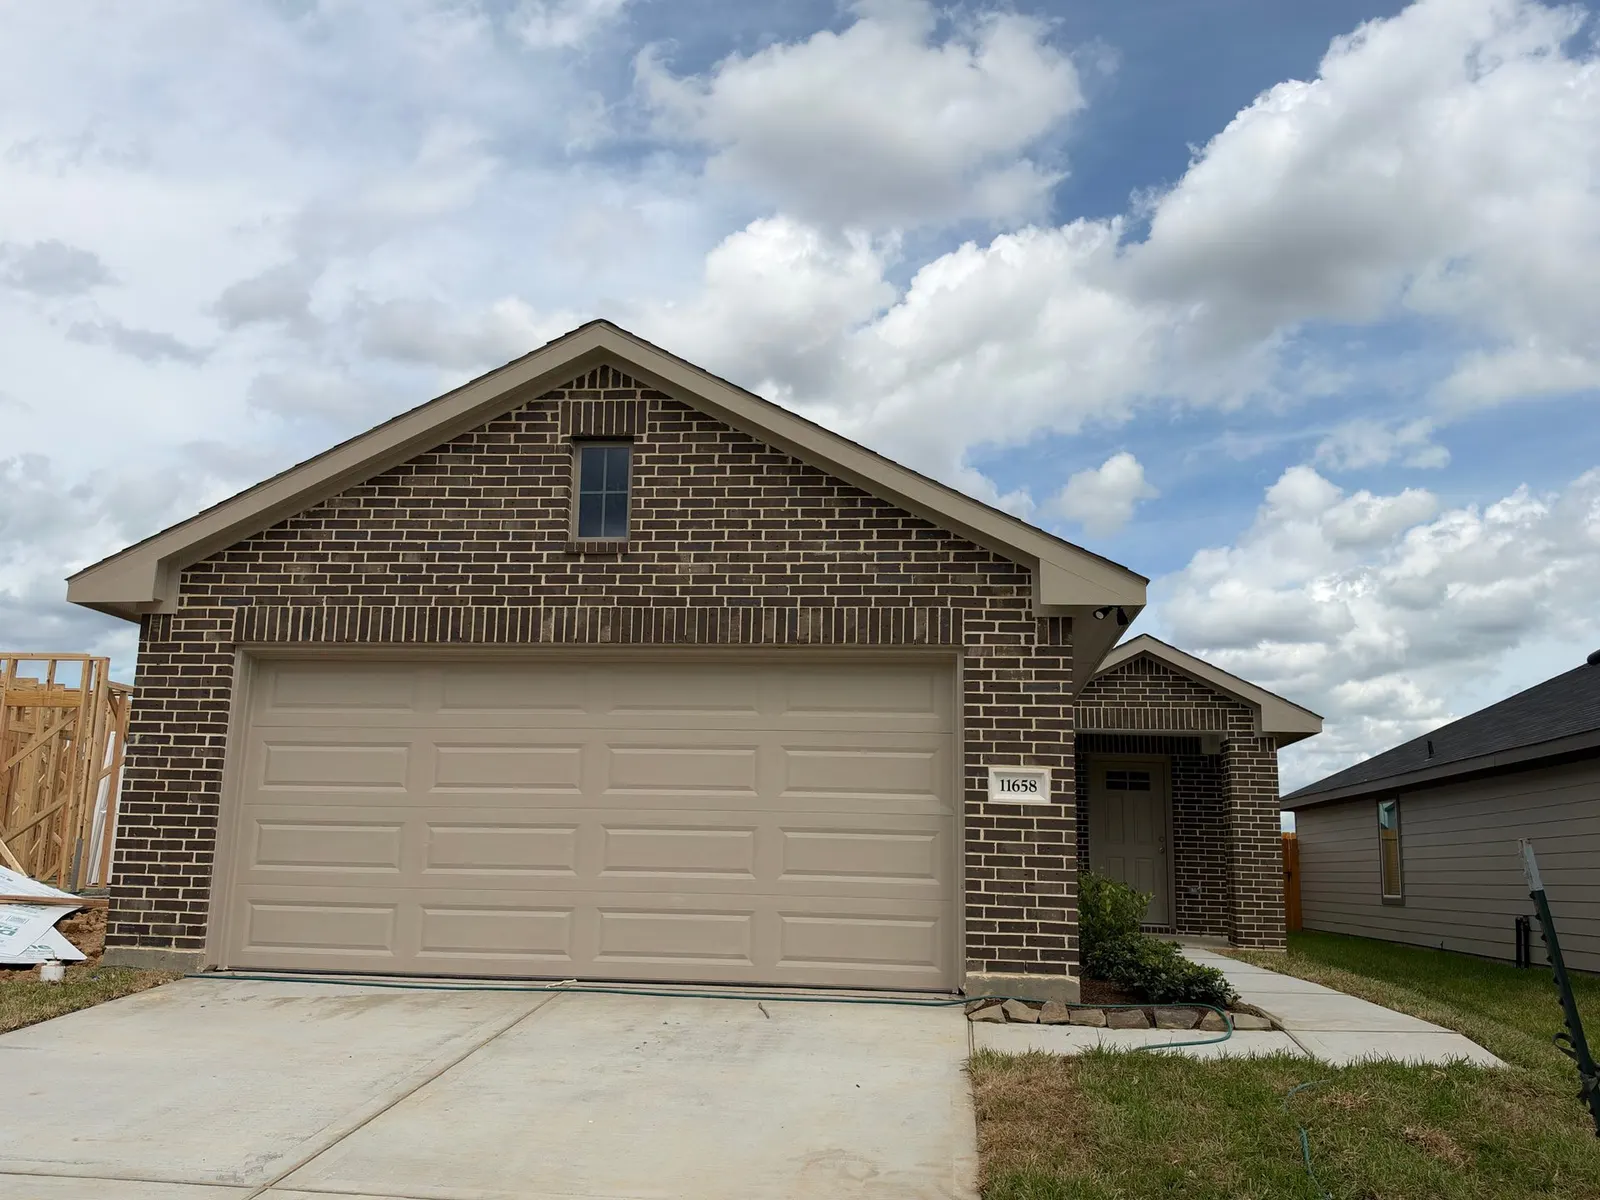
Lake Conroe Village in Montgomery, Crockett Meadows in Conroe, and Lexington Heights in Willis provide different starting points for a search. Their pages show the floor plans, community information, and currently published homes.
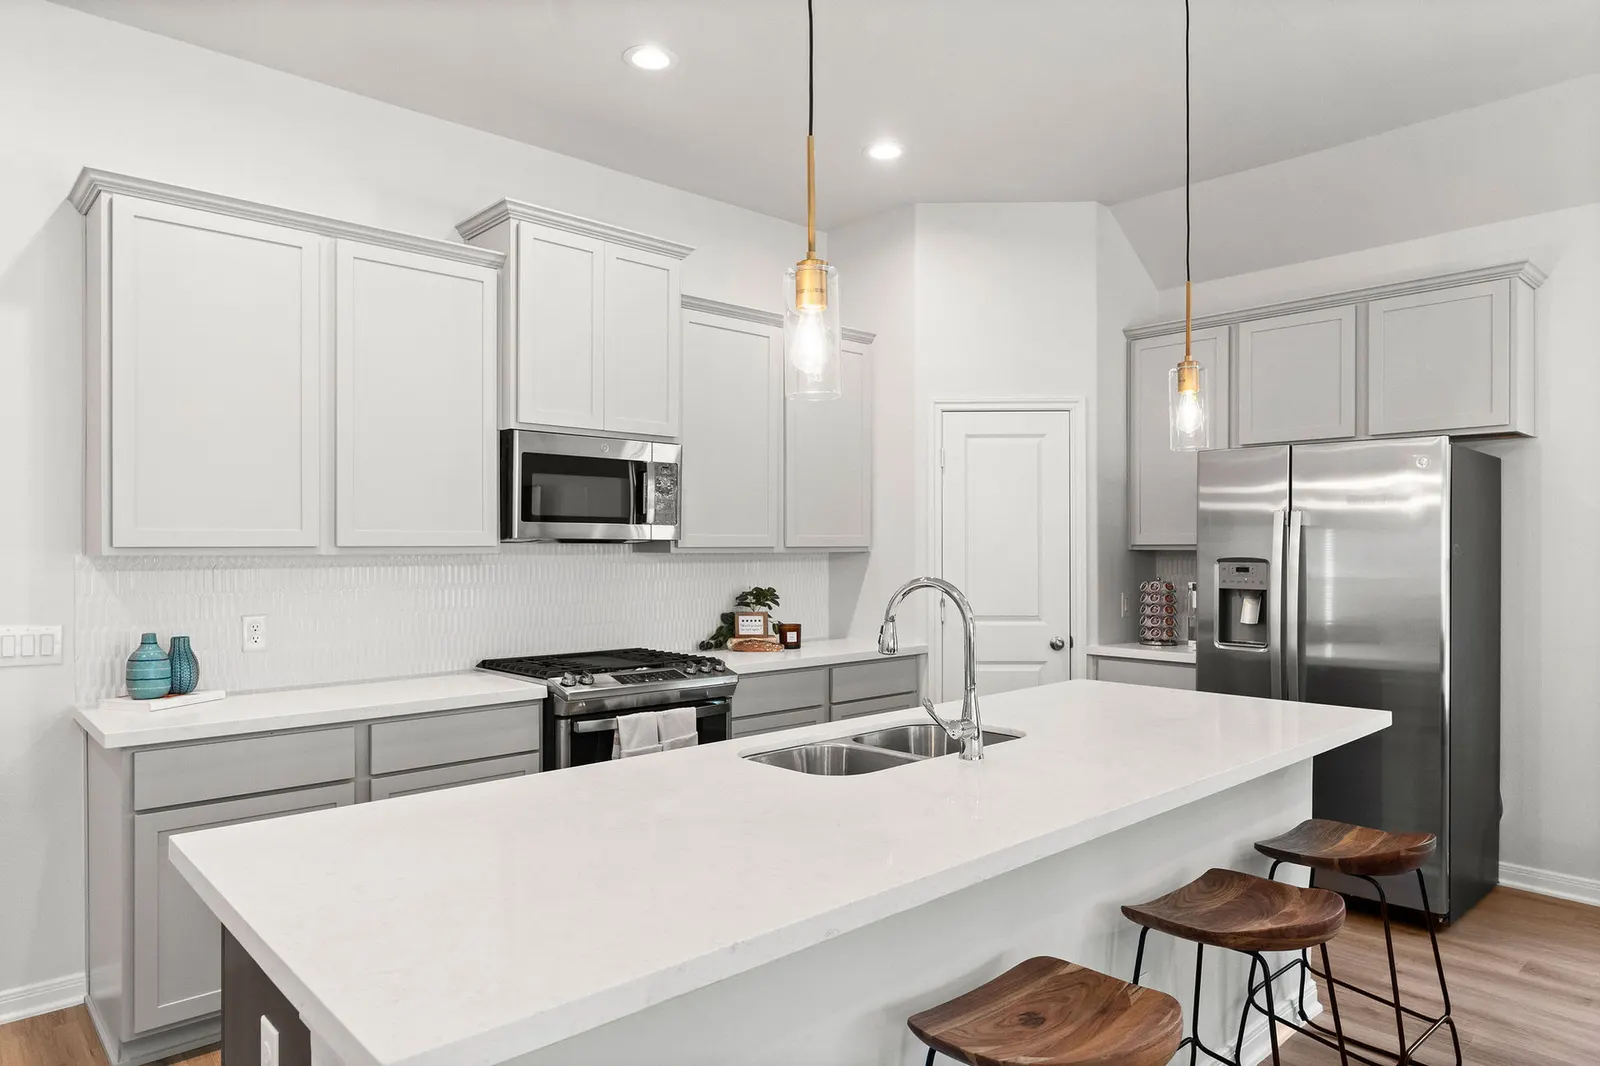
Compare the homes that meet your requirements rather than assuming a community is intended only for downsizers. Use each included-features sheet to check appliances, finishes, and other items for the specific home. Model-home furnishings and optional details should not be treated as part of every purchase.
The Alta Standard links to those documents. Warranty information explains where to find coverage and service details; a new home still needs routine maintenance.
Coordinate the move before committing
Ask the Home Advisor about expected availability and how construction updates are shared. Discuss your current sale or lease with your real estate representative and lender. Set out which events must occur before you can close and what flexibility the contract provides.
Before accepting an offer or signing for the next home, have a clear picture of your likely proceeds, the next purchase’s costs, and the savings left afterward. It may make sense to move now, adjust your search, or stay longer. The useful result is a home and budget that suit your plans.