Should You Wait for Mortgage Rates to Drop?
Homebuyer Tips Jun 29, 2026 · 3 min read Updated: Sep 8, 2026
A lower mortgage rate can change a payment, but there is no reliable way to choose a purchase date by predicting rates alone. Compare a home you could afford today with a realistic plan for waiting.
Use an offer you can actually obtain
Start with lender figures for your situation and a specific property. Keep the loan amount, down payment, and term consistent when comparing options. An advertised national rate or a builder’s earlier promotion may not describe the loan available to you.
The interest rate and annual percentage rate serve different purposes. APR includes certain borrowing costs in addition to interest, so it can help you examine the cost of an offer. The CFPB explains the distinction between rate and APR.
Compare two practical scenarios
For buying now, include the current home’s price, financing offer, ownership expenses, and cash required. For waiting, consider your expected savings, current housing cost, and likely change in personal circumstances.
Label uncertain inputs as assumptions. Home prices, rates, rents, and available inventory can move in different directions. A lower future rate does not guarantee a lower overall purchase cost, and buying today does not guarantee a better outcome.
Try a scenario in which rates do not fall. If waiting still helps you build reserves or clarify where you want to live, it may have value independent of the market.
Read incentive terms carefully
Ask whether a payment reduction is temporary, whether points are being paid, and what rate and payment apply later. Confirm eligibility, the deadline, lender requirements, and the specific homes covered by the offer.
The CFPB’s explanation of points and lender credits describes the tradeoff between upfront costs and the interest rate. Request a comparison that shows both, rather than considering only the first payment.
Do not make a future refinance essential
Refinancing replaces a mortgage with another loan and has its own terms and costs. The CFPB’s mortgage terminology guide explains the basic arrangement.
A future approval or favorable rate cannot be assumed. Ask whether you would still be comfortable with the home if the original loan remained in place. Include taxes, insurance, and maintenance that could change independently of the mortgage rate.
Decide what would make you ready
A payment within your budget, adequate savings after closing, a suitable location, and a workable timeline are more actionable conditions than a prediction about the next rate announcement.
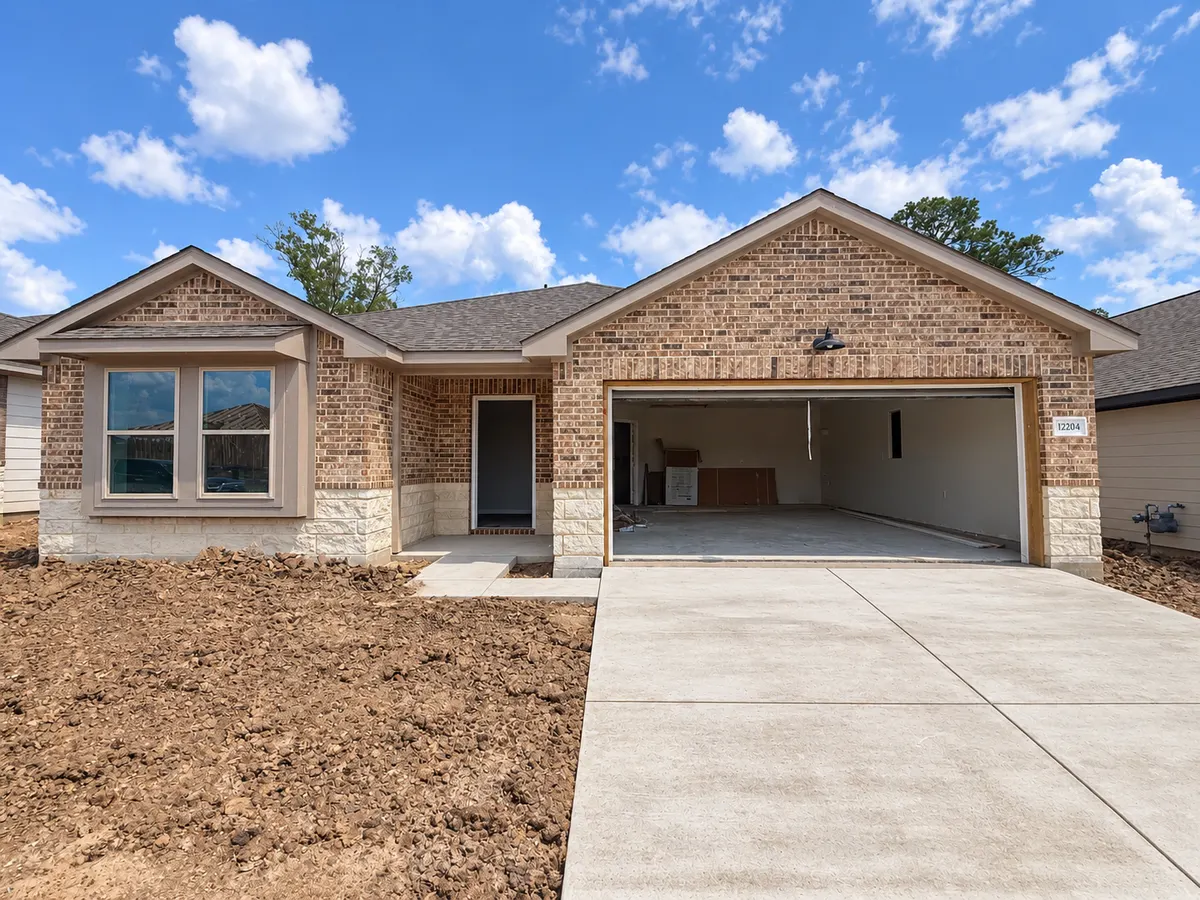
Use available Alta homes to identify properties for a current lender comparison. If you need time to save, reduce uncertainty, or prepare for a move, waiting can be a sound choice. The decision should fit your budget, timing, and the homes available to you.