Finding Homebuying Options Within Your Budget
Homeowner Info May 6, 2025 · 3 min read Updated: Sep 8, 2026
A useful home search begins with a budget you can sustain and a clear view of the options available. Loan programs and assistance may change what is possible, but their terms should be checked before you choose a home around them.
Define a search range that fits your plans
Write down your preferred monthly housing total, the money available for the purchase, and the savings you want to retain. Include the costs of your current lease or sale and the date by which you hope to move.
Separate the features you need from those you would like. Location, bedrooms, stairs, parking, and expected availability may narrow the search more usefully than a broad maximum price.
Compare homes across a manageable area
Choose a few locations that could work for your routine. Test your commute and check services using the actual property address. A lower price farther away may introduce costs or travel time you would prefer to avoid.
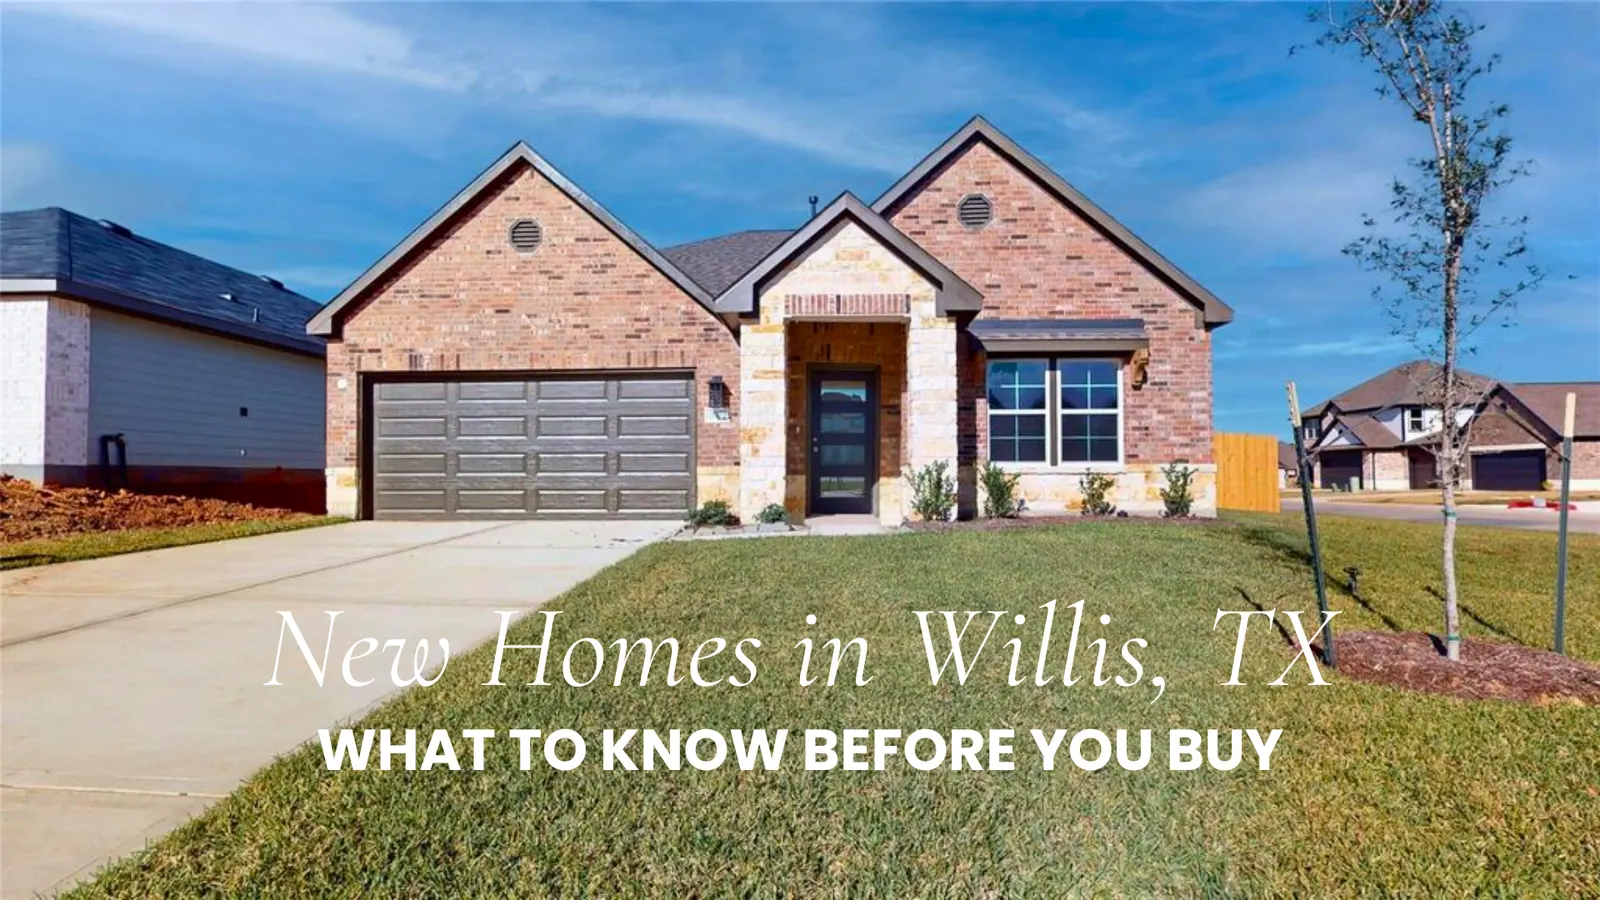
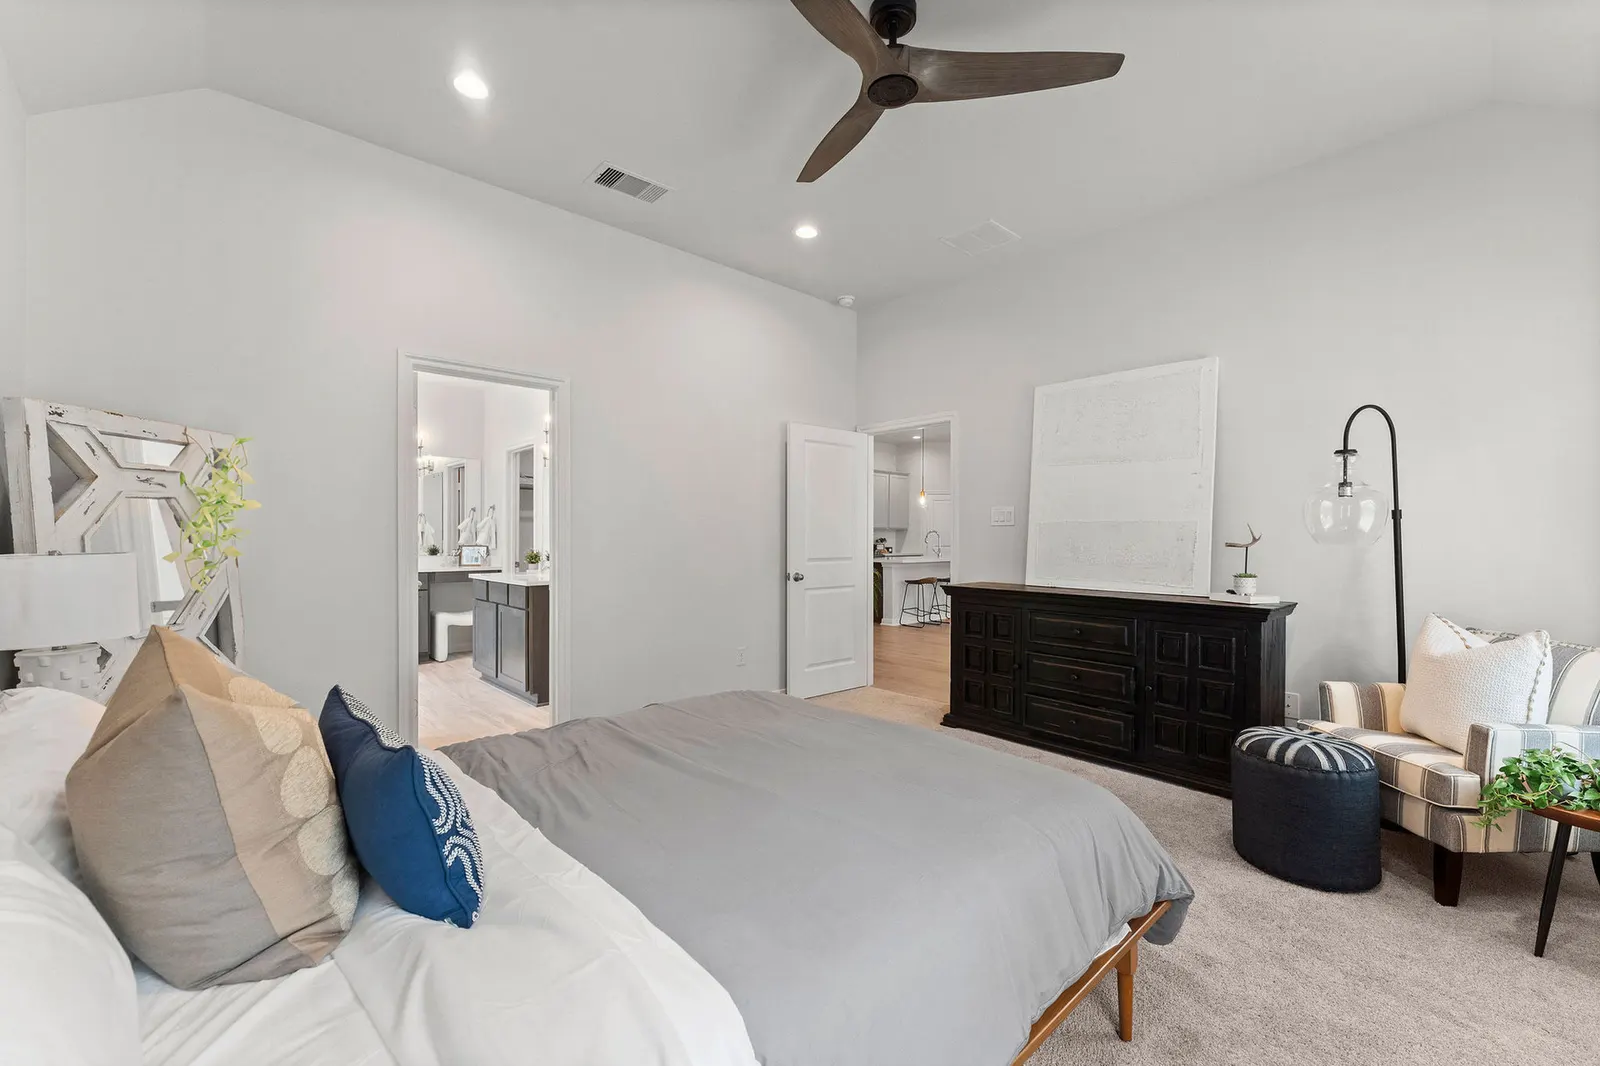
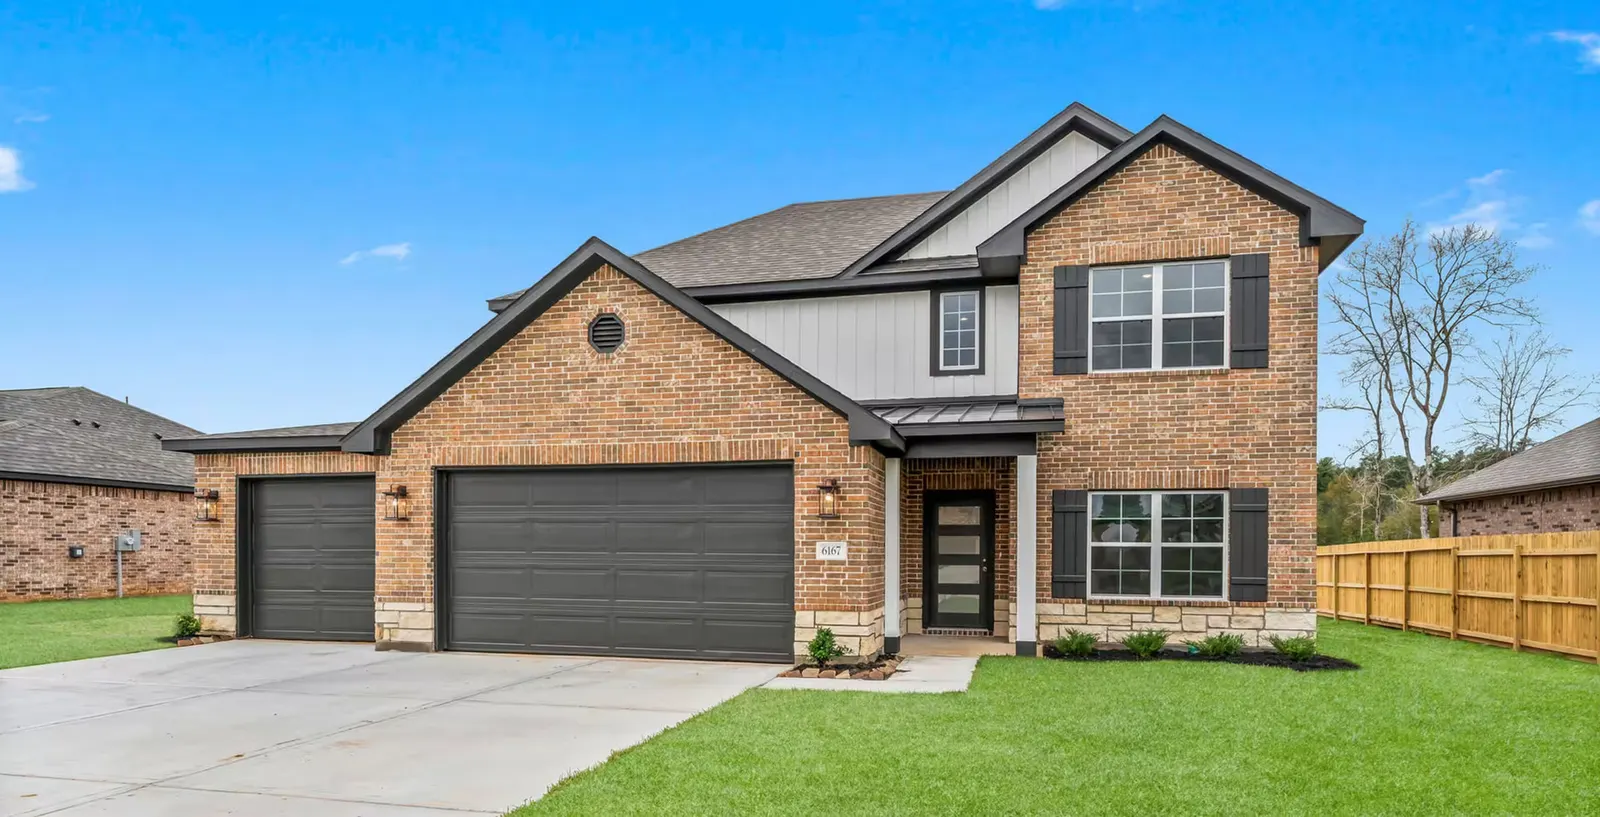
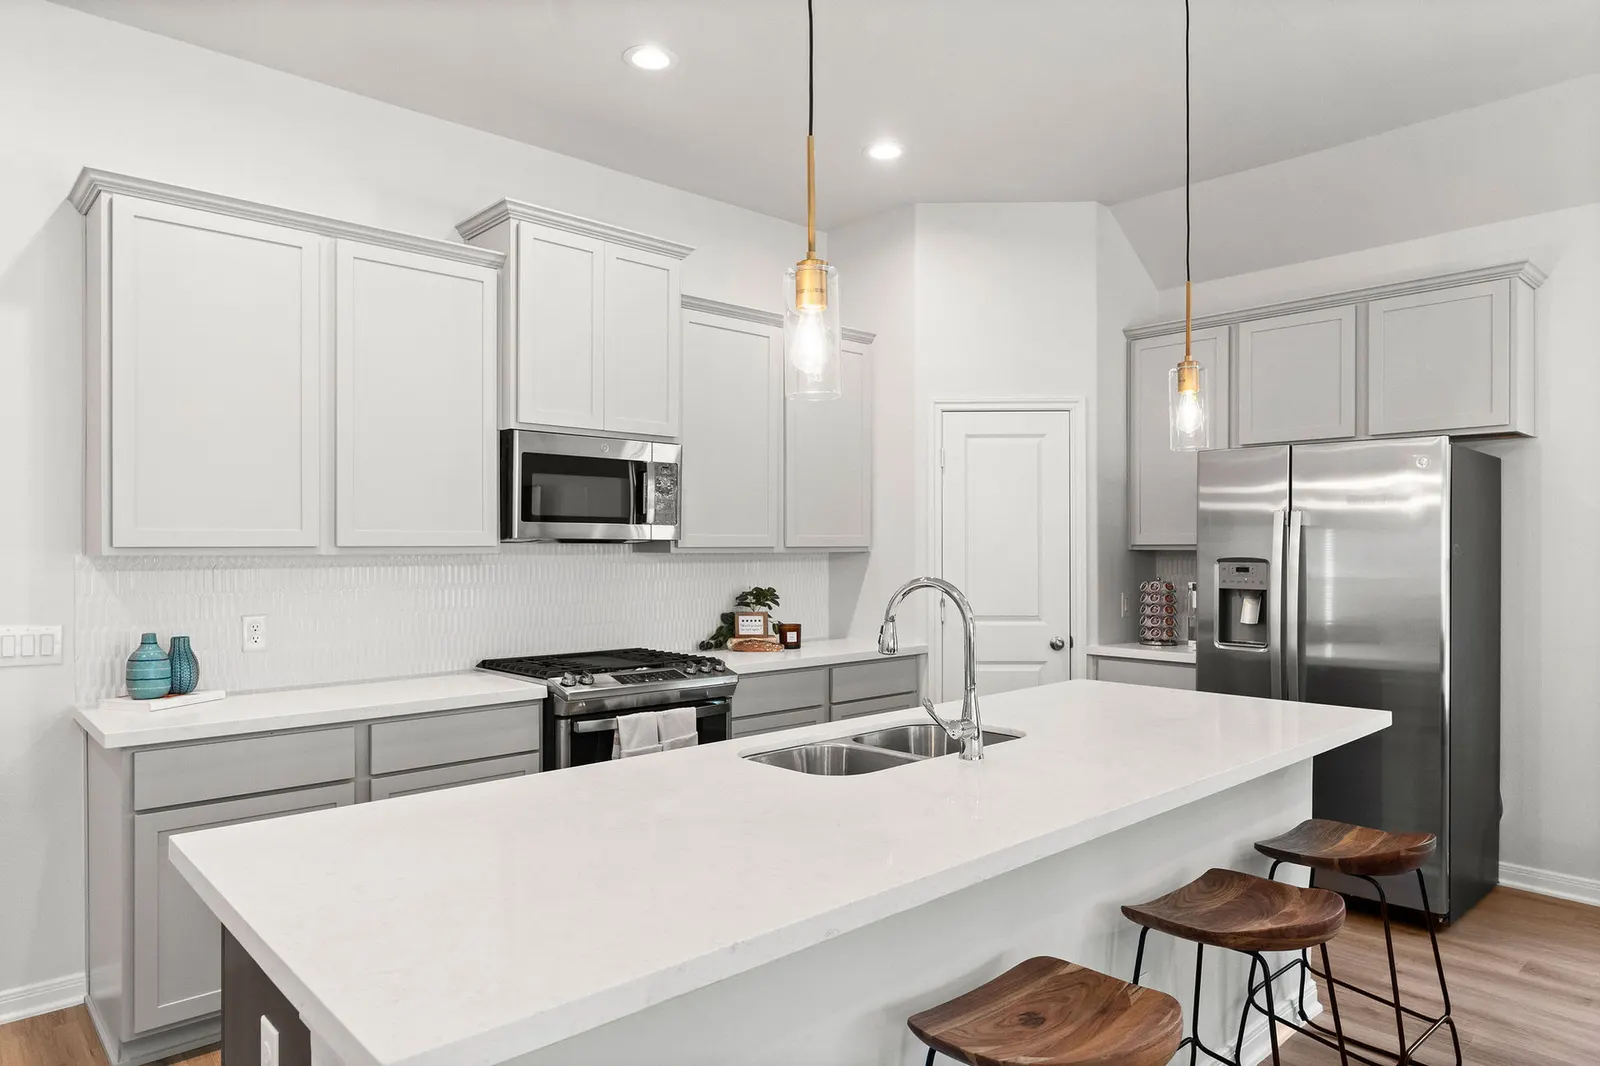
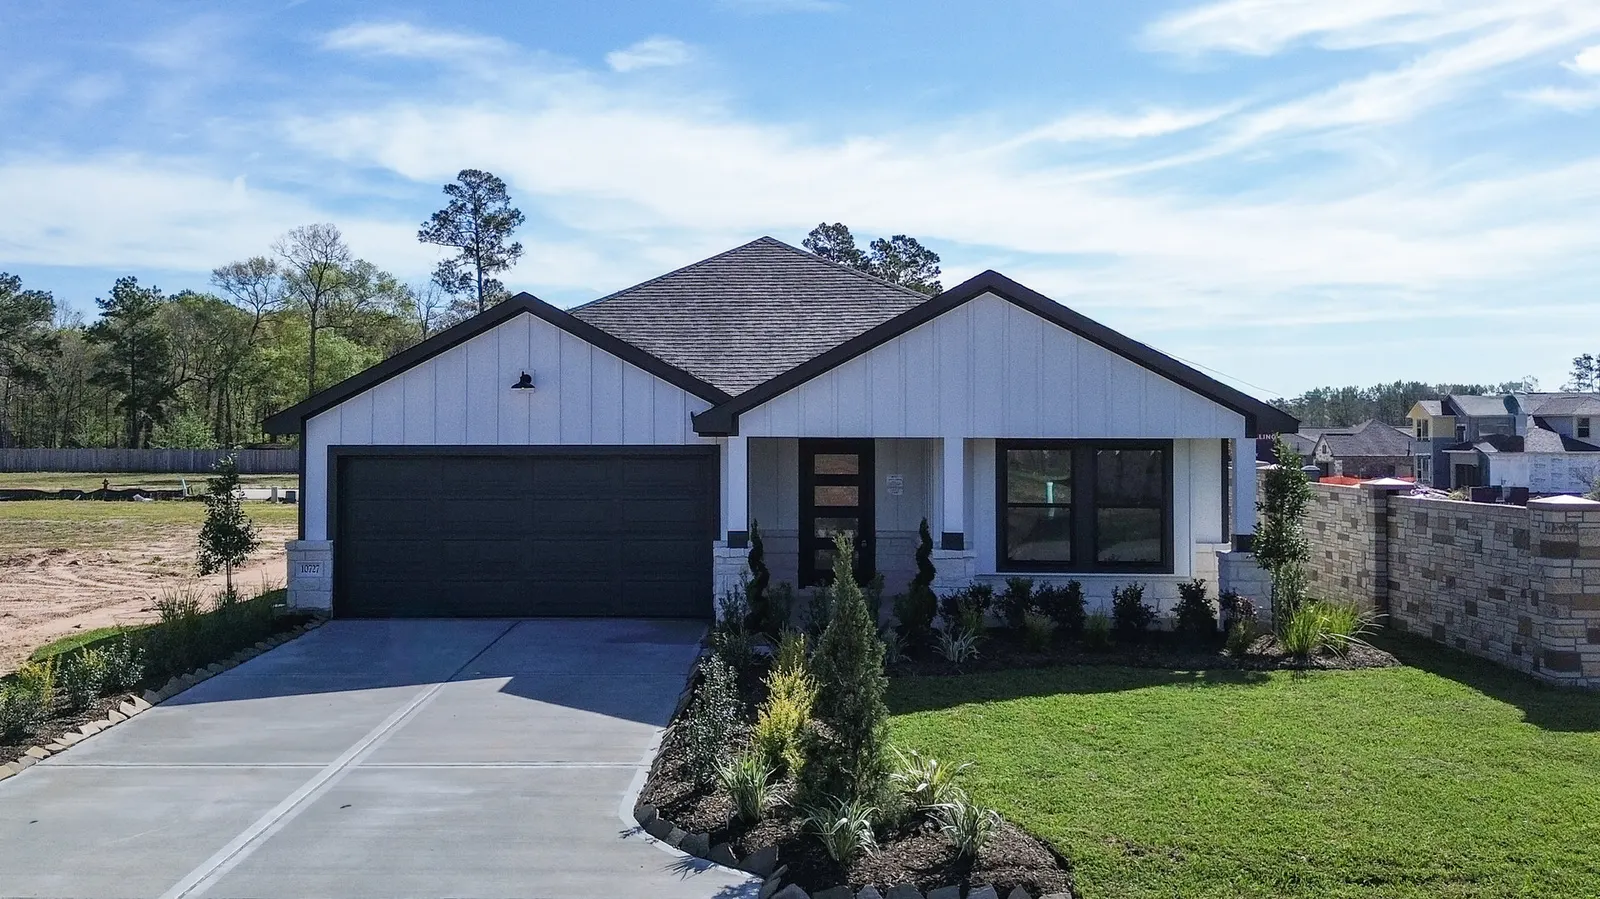
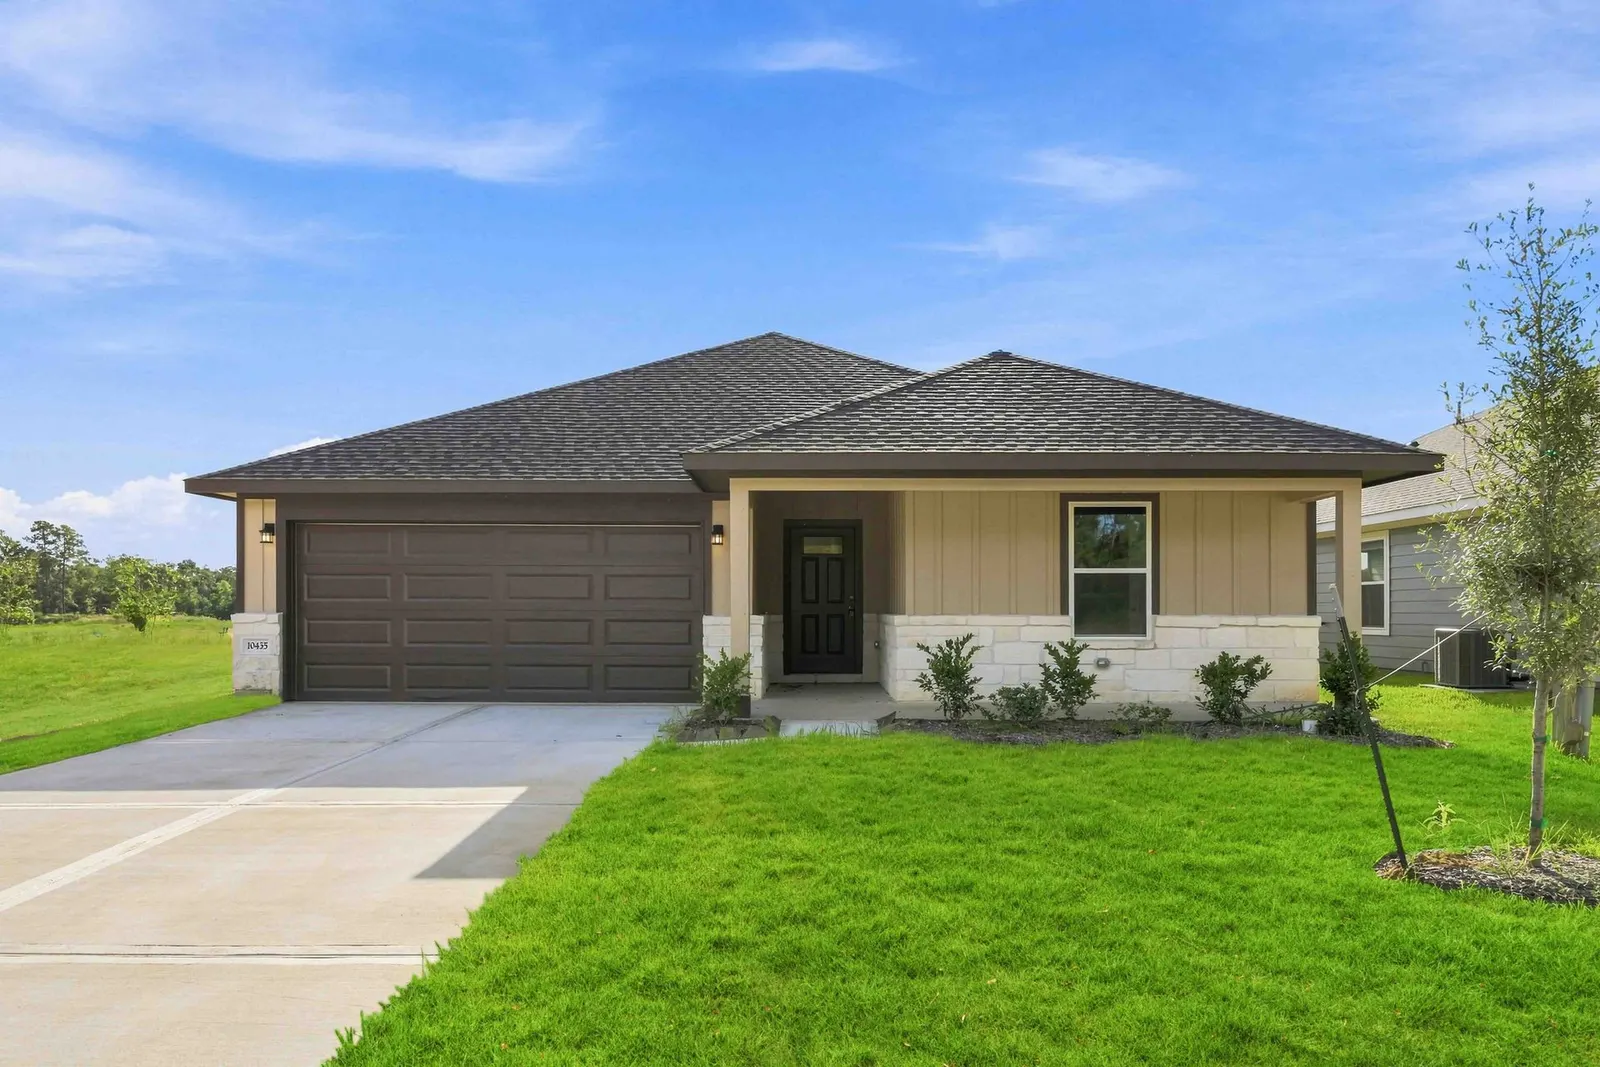
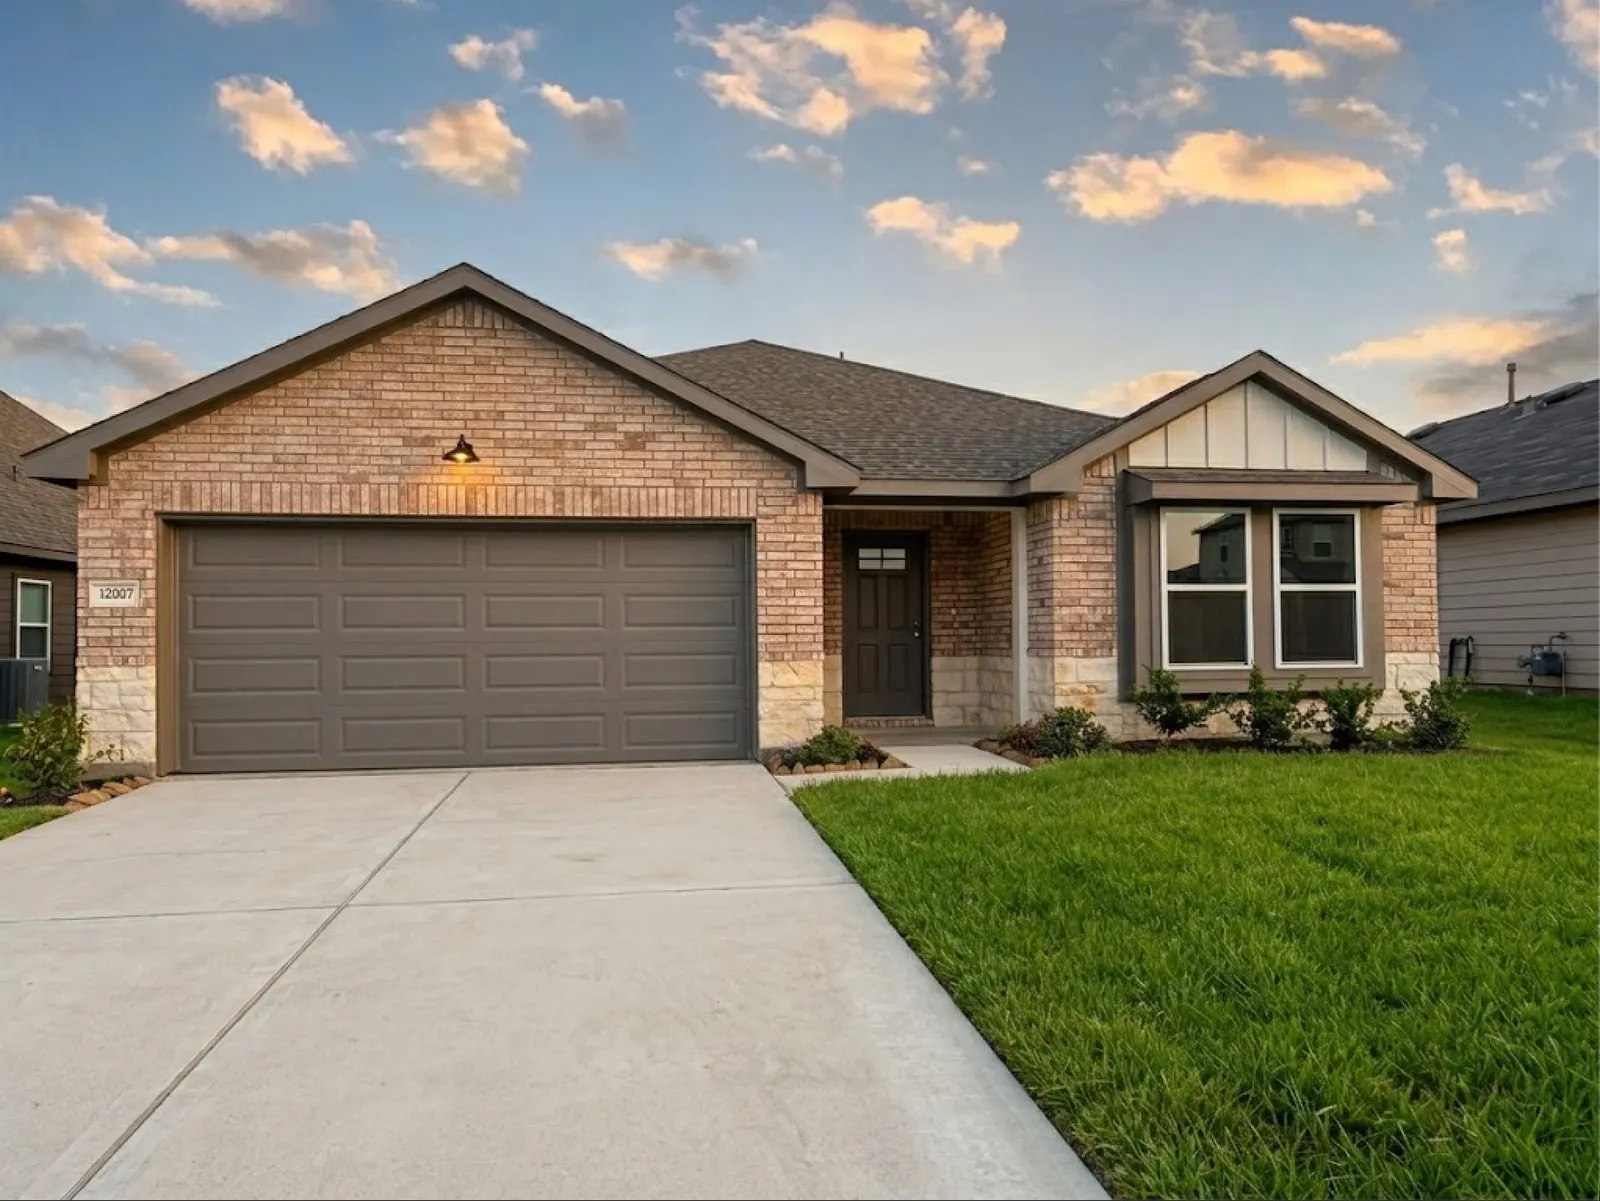
Compare current Alta communities and available homes. Look at the floor-plan arrangement and included features alongside the purchase price.
Review assistance eligibility and terms
There is no single homebuyer grant that applies automatically to everyone in Texas. Eligibility, funding, repayment terms, and purchase limits depend on the specific program.
The Texas Department of Housing and Community Affairs’ program directory provides an official starting point. Ask a participating lender which options fit your household and property, and request the obligations in writing.
A program may help with upfront costs while affecting the loan terms. Compare the total arrangement, including any separate assistance loan, with a loan that does not use the program.
Shop for the loan as well as the home
Request comparable offers using the same purchase price, down payment, and loan type. Look at the payment, cash required, interest rate, fees, and any conditions. The CFPB’s mortgage-shopping guidance outlines questions to bring to lenders.
If an estimate changes, ask what caused the difference. Check whether taxes and insurance were revised, the rate changed, or a credit was added. Do not assume a lower headline payment means the entire purchase costs less.
Leave time for the transaction
Before signing, review the contract, deposit requirements, inspections, financing conditions, and expected closing date. If a home is still being built, ask how changes to completion timing are handled.
Review the Alta Standard and warranty information for the documents that apply to the home. These details help you budget for both move-in and ownership.
If the numbers do not fit, adjust the home, location, timing, or savings plan and compare again. A lender or housing counselor can help identify the next information to gather; no one conversation or assistance program guarantees approval.